

How You Can Claim
Land Remediation Relief (LRR)
Are you entitled to 150% tax relief on your land remediation costs?
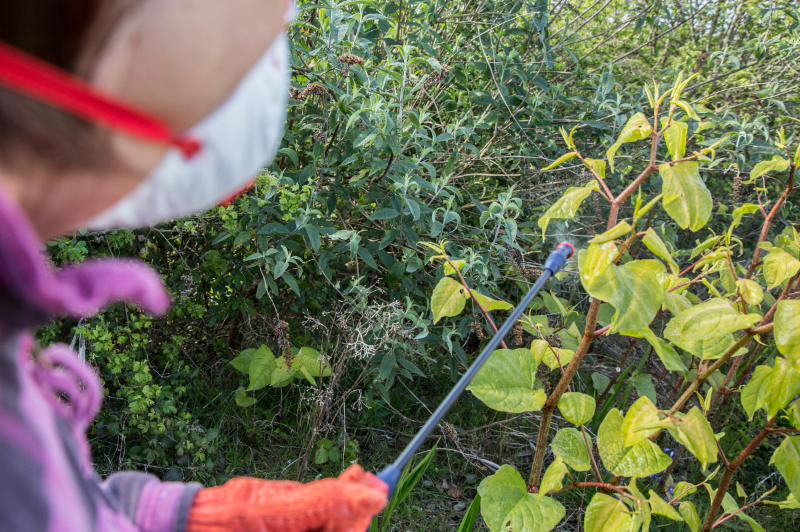
Removing asbestos as part of a renovation project, cleaning up brownfield sites for development, or even eliminating knotweed from your grounds often involves costly remediation work. For example, these could include risk assessments, decontamination, and the removal of invasive plants, hazardous materials and buried structures.
However, if you’re a UK commercial owner occupier, investor, life assurance company, or developer who has acquired a major interest in a contaminated or derelict site, you could benefit from Land Remediation Relief (LRR).
LRR was introduced as an incentive to clear contaminated land by removing cost barriers – in turn, increasing the supply of developed land to meet housing needs. What LRR could mean to you is that costs incurred from your remediation work may entitle you to corporation tax relief of up to 150% of that expenditure.

What costs are covered?
LRR includes business expenditure on a range of essential remediation services. These include everything from preparatory costs, risk assessments, staffing costs and materials to services contracted out and sub-contracted expenditure, such as asbestos removal, remediation works, survey fees and environmental consultancy fees.
Can I claim?
First and foremost, you have to be a company to claim. Another way is that individuals and partnerships are not able to claim.
You must acquire land and buildings in the UK for your own business purposes or as a property investment. You must be a freeholder or hold a long lease (originally granted for at least 7 years). Past industrial activity not connected to you must have contaminated the land at the time of acquisition.
Investors and owner-occupiers must claim LRR at 150% within two years of expenditure. Developers can claim LRR at 50% on qualifying costs within four years of expenditure.
How we can help
Claiming LRR is simple. Once you have completed our fact-finding questionnaire, we’ll assess your eligibility, arrange a technical meeting and review your eligible expenditure. You claim your company tax return after the accounting year ends. We will prepare the LRR report to satisfy HMRC and attach it to the tax return.
If you have any questions on Land Remediation Relief, please get in touch.
You can read the Frequently Asked Questions related to LRR here.
Get your FREE guide to LRR.

